

myWisely: Mobile Banking
by ADP, INC.
4.3
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.3
- Price
- Free
- Download
- 5.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
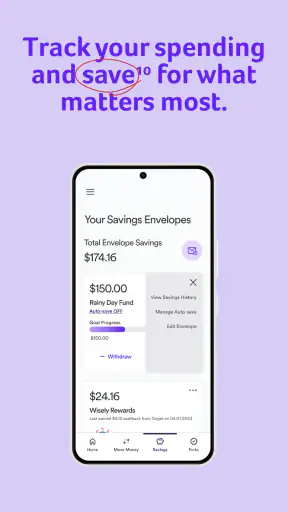
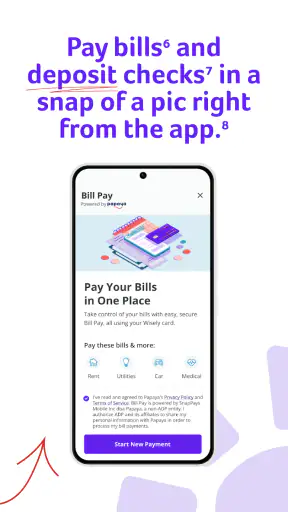
 Analysis by Getfullapps
Managing money from a phone sounds simple until an app leaves you wondering where your pay went, what you can safely spend, or how to build a little savings habit. myWisely: Mobile Banking is designed around that everyday problem. It is a free finance app from ADP, INC. that brings pay access, spending awareness, and saving tools into one mobile experience. I see it as a practical companion for people who already use Wisely services through work, rather than a universal replacement for a full traditional bank.
My first impression is that the app makes more sense when you approach it with one immediate goal. You might want to check whether your pay has arrived, review recent spending, or set money aside. Those are clearer starting points than opening it expecting a complete financial-planning suite. The store summary, “Get paid. Track spend. Save more,” captures the basic direction, but the useful question is whether that direction fits your routine.
What to expect before you begin
The app sits in the mobile banking side of the finance category, with an average rating of 4.3 from around 31 thousand ratings and more than 5 million installs. That level of adoption suggests it is not an obscure experiment, but popularity should not be confused with suitability. Its value depends heavily on whether your pay or account setup connects naturally with Wisely.
I would recommend approaching it as a focused money-management tool. It can help you see activity in one place and make more deliberate decisions after payday. It is less convincing for someone who wants a broad banking relationship with many account types, extensive investing features, or a desktop-first budgeting system. Those users may feel more comfortable with a conventional bank app or a dedicated budgeting service.
The free price is an important advantage for a first-time user because there is no app purchase standing between you and trying the basic experience. The content rating is Everyone, so the presentation is intended for a broad audience. The current version is 26.6.0, and the app requires an operating system version of 10 or later. Before installing, I would check the software version on an older phone, especially if the device is no longer receiving regular updates.
One useful mindset shift is to separate “seeing money” from “improving money habits.” The app can make balances and activity easier to follow, but it cannot decide which spending is necessary or create a savings plan that fits your life without your input. I found it most helpful when treated as a short daily check-in, not as something that replaces judgment.
Who will get the most from it
myWisely is a strong match for a first-time mobile banking user who wants a straightforward place to monitor pay and spending. It can also suit someone who tends to discover financial problems late, such as noticing an unexpectedly low balance only after several small purchases. A quick glance at recent activity can make those patterns visible earlier.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
It is also useful for people who prefer a phone-based routine. If you rarely sit down at a computer to review finances, a mobile app lowers the effort required to check in. That matters because a simple habit repeated often is usually more useful than an elaborate budget opened once a month.
I would be more cautious if you need detailed joint-money management, complex categorization, long-term investment tracking, or highly customizable reports. The app’s appeal is its directness. Once your needs move beyond pay, spending, and saving, a broader financial platform may be the better choice.
Setting up the app without getting stuck
For a smoother first session, I would install the app when you have your relevant account or pay information nearby. Rushing through setup while commuting or standing in a checkout line makes it easier to enter the wrong detail or misunderstand which account you are viewing. A calm first login gives you time to read each screen rather than treating setup as a formality.
After opening the app, start by confirming that you are using the correct Wisely credentials or account path for your situation. This is an important distinction for new users: the application is not simply a blank banking dashboard that becomes fully useful without an associated Wisely relationship. If you expect it to import every outside bank account automatically, you may be disappointed.
Once you reach the main account view, pause before exploring every menu. First identify the displayed balance, recent activity, and the area connected with pay. That small orientation step prevents a common beginner mistake: assuming the first number on screen represents money available for every possible transaction. Balances, pending activity, and incoming pay can have different meanings in a banking context.
I also recommend completing setup over a trusted connection and keeping your login details private. Avoid saving sensitive information in notes or sending screenshots of account screens to other people. These are ordinary precautions, but they matter more when an app gives you a convenient view of money that you may check frequently.
Make the first screen work for you
Your first useful task should be simple: find the latest account activity and compare it with what you remember spending. Do not begin by trying to create a perfect financial system. The purpose of this first check is to learn how the app presents transactions and how quickly you can find the information you care about.
A helpful routine is to open the app after a known pay event, confirm the relevant activity, and then look at the balance before making discretionary purchases. That sequence connects income with decisions. It is more practical than checking a balance in isolation because it encourages you to ask what has already been committed.
Another good early habit is to review small purchases rather than only large bills. Several modest transactions can change your available money without feeling significant individually. The spending view becomes valuable when you use it to notice repetition: frequent convenience purchases, recurring charges, or a cluster of expenses during a busy week.
Your first meaningful success: turn a check into a routine
For me, the first real success with myWisely is not merely logging in. It is completing a short cycle: confirm that money arrived, inspect recent spending, and decide what can safely remain untouched. That cycle takes the app’s three main ideas—getting paid, tracking spending, and saving—and turns them into a concrete behavior.
Imagine receiving pay before a weekend. Instead of immediately treating the full amount as available, you open the app, review the latest activity, and separate planned obligations in your mind from flexible spending. If the app’s saving tools fit your account setup, you can use that moment to move toward a savings goal or preserve part of the balance. The important benefit is the pause before spending.
I would repeat this check at a consistent point in your pay cycle. The exact day is less important than choosing a moment you can remember. A short review after income arrives can reveal whether your previous plan was realistic. If you repeatedly run short before the next pay event, the app may help you see the pattern, but you still need to adjust the underlying choices.
One non-obvious advantage of this approach is that it reduces dependence on memory. People often remember major purchases and forget the small ones that accumulate. Looking at actual activity gives you a more honest picture than estimating from feeling. I found that this makes the saving decision less abstract because it is based on what really happened in the account.
Using spending information wisely
Do not treat a spending screen as a judgment of your lifestyle. Use it as evidence. If you notice that one type of purchase appears repeatedly, ask whether it is planned, necessary, or simply convenient. The app cannot answer that for you, but it can make the question easier to ask at the right time.
A practical technique is to review activity in two passes. In the first pass, look for anything unfamiliar or unexpected. In the second, look for patterns among purchases you recognize. This prevents you from focusing only on suspicious-looking transactions while overlooking ordinary spending that is quietly affecting your balance.
Saving also works better when it has a purpose. Rather than vaguely deciding to save more, choose a reason such as creating a cushion for an upcoming need. Then use the app as a place to check whether your behavior is moving in that direction. If moving money aside would leave too little for essential expenses, protecting your day-to-day stability should come first.
This is where myWisely differs from a traditional bank app that may focus mainly on balances and transfers. Its identity is more closely tied to the connection between pay, spending, and saving. A dedicated budgeting app may offer deeper planning, but it can also require more manual organization. The trade-off is convenience versus detail.
Common points of confusion for new users
The first confusing issue is often the difference between the app and the broader Wisely service. Installing the application does not automatically mean that every financial account you own will appear inside it. I would begin by identifying the specific Wisely account or pay arrangement you intend to manage. That keeps expectations realistic and makes the first screen easier to understand.
Another source of confusion is assuming that a displayed balance answers every spending question. A balance is a snapshot, while recent activity provides context. If you have just been paid or have recently made purchases, give yourself time to inspect the activity rather than relying on one prominent number.
Users can also expect the saving function to solve budgeting by itself. It cannot. Setting money aside may be helpful, but the amount must still fit your upcoming needs. I would make saving decisions after reviewing recent activity, not before. That order reduces the chance of creating a shortfall simply because a savings action felt productive.
There is also a practical limitation in comparing it with a full-service bank application. A traditional bank may be preferable if you need a wider range of financial products or a more comprehensive overview of accounts outside the Wisely environment. Conversely, a budgeting app may be better if your main goal is detailed category analysis across several institutions. myWisely is most convincing when its focused workflow matches your actual account and pay needs.
When the app may not be the right fit
I would skip it if you are looking for investment research, advanced financial forecasting, or a complete household accounting system. Those goals require a different kind of tool. Adding another app will not help if the real problem is that you need consolidated information from several unrelated accounts.
I would also think twice if your phone cannot meet the minimum operating-system requirement. An unsupported device can create avoidable frustration, particularly in a finance app where reliability matters. In that situation, updating the phone or using an alternative supported banking method may be more sensible than forcing the installation.
Finally, users who dislike checking money regularly may not experience much benefit. The app can make information accessible, but it cannot create attention. If you open it only after a problem appears, you will miss much of its value. Its strongest use is preventative: checking before a spending decision, not merely investigating afterward.
The next step after your first week
After several check-ins, I would evaluate whether the app is helping you answer three practical questions quickly: Has expected pay arrived, what has changed since the last review, and how much can you responsibly leave untouched? If those answers are becoming easier to find, the app is earning its place on your phone.
At that point, build a small personal routine around the information you actually use. You might check after pay arrives, review activity before a larger weekend expense, and look at your saving progress during a quieter moment. Keeping the routine short is important. A system that takes too much effort is unlikely to survive a busy month.
One advanced but realistic use is to treat the app as an early-warning tool. Instead of waiting for an empty balance, watch for changes in spending frequency. If familiar purchases begin arriving earlier or more often, that may signal pressure on your budget before the final amount becomes alarming. This is a behavioral insight rather than a special feature, but the app’s quick access makes it easier to act on.
Another useful trade-off is deciding whether simplicity is more valuable to you than consolidation. If most of your relevant money activity belongs within the Wisely setup, a focused app can be less tiring than a platform filled with tools you never use. If your finances are spread across multiple institutions, consolidation may matter more, and another option could provide a clearer overall picture.
ADP, INC. has positioned this as a free mobile finance app rather than an expensive specialist product, and its broad audience rating supports an approachable first step. Still, I would judge it by your daily workflow, not by its install count or rating alone. The right app is the one that helps you make a better decision when you need it.
My final view after using it
I like myWisely because it gives first-time users a clear starting point: look at pay, understand spending, and make room for saving. The experience is most useful when you keep the goal modest and repeatable. Checking activity before spending and reviewing the balance after income arrives can turn a vague sense of financial stress into specific information.
Its limitations are equally important. It is not the best answer for every banking need, and it should not be mistaken for a full financial-planning system. The relationship with Wisely matters, the supported device requirement matters, and the app still depends on users making sensible decisions with what they see.
For someone who wants a free, phone-based way to stay closer to pay and everyday spending, I think it is worth trying. I would install it, complete setup without rushing, find the latest activity, and make that three-part review—income, spending, and money to preserve—the first meaningful task. The best result is not simply knowing your balance; it is making your next money decision with fewer surprises.
Pros
- Early direct-deposit access may make funds available before payday.
- Card controls help users lock the card and manage spending from the app.
- No monthly fee is typically charged for the standard Wisely account.
- In-app alerts can help track purchases and monitor account activity.
- The app supports mobile check deposit for eligible users and checks.
Cons
- Availability and features may depend on the employer’s Wisely program.
- Some out-of-network ATM withdrawals can involve additional fees.
- Early deposit timing is not guaranteed and varies by payroll provider.
- Cash reload options may be limited by location and retailer availability.
- Customer support and account issues may take time to resolve.
FAQs for myWisely: Mobile Banking
What is myWisely: Mobile Banking used for?
myWisely: Mobile Banking is designed for Wisely cardholders who want to manage their prepaid debit account from a phone. After signing in, users can typically review their available balance, check transaction history, receive account notifications, locate participating ATMs, and manage selected card settings. The exact tools available may depend on the Wisely card program issued through your employer or financial institution.
Is myWisely: Mobile Banking free to download and use?
The myWisely app is generally available as a free download for compatible Android and iOS devices, but downloading the app does not mean every account service is free. Certain activities, such as out-of-network ATM withdrawals, expedited transfers, replacement cards, or other optional services, may involve fees. Before using a feature, review the fee information connected to your specific Wisely account.
How do I sign in to myWisely if I am a new user or forgot my password?
New users normally need to register with information associated with their Wisely card or account, such as card details and personal identification information. If you forget your login credentials, use the recovery option on the sign-in screen and follow the verification steps. Keep your phone number and email address current, since the app may use them for security codes or account recovery.
Can I use myWisely to transfer money, deposit checks, or access cash?
The app may provide several money-management options, but availability varies by card type, state, employer program, and account eligibility. Depending on your account, you may be able to transfer funds, receive qualifying direct deposits, deposit checks through an available mobile feature, or find surcharge-free ATMs. Carefully check processing times, limits, eligibility rules, and applicable fees before initiating a transaction.
Is my money and personal information secure in the myWisely app?
myWisely uses account authentication and security controls intended to protect card and financial information, and users should keep the app updated to receive important fixes. However, no mobile service is completely risk-free. Use a secure device, avoid public Wi-Fi for sensitive activity, enable available biometric or passcode protection, never share verification codes, and contact official Wisely support immediately if you notice suspicious transactions.

myWisely: Mobile Banking
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via mywisely_feedback@ADP.com, visit http://www.mywisely.com, or review their https://www.mywisely.com/app/main/assets/html/Wisely-Online-Privacy-Statement.html.










